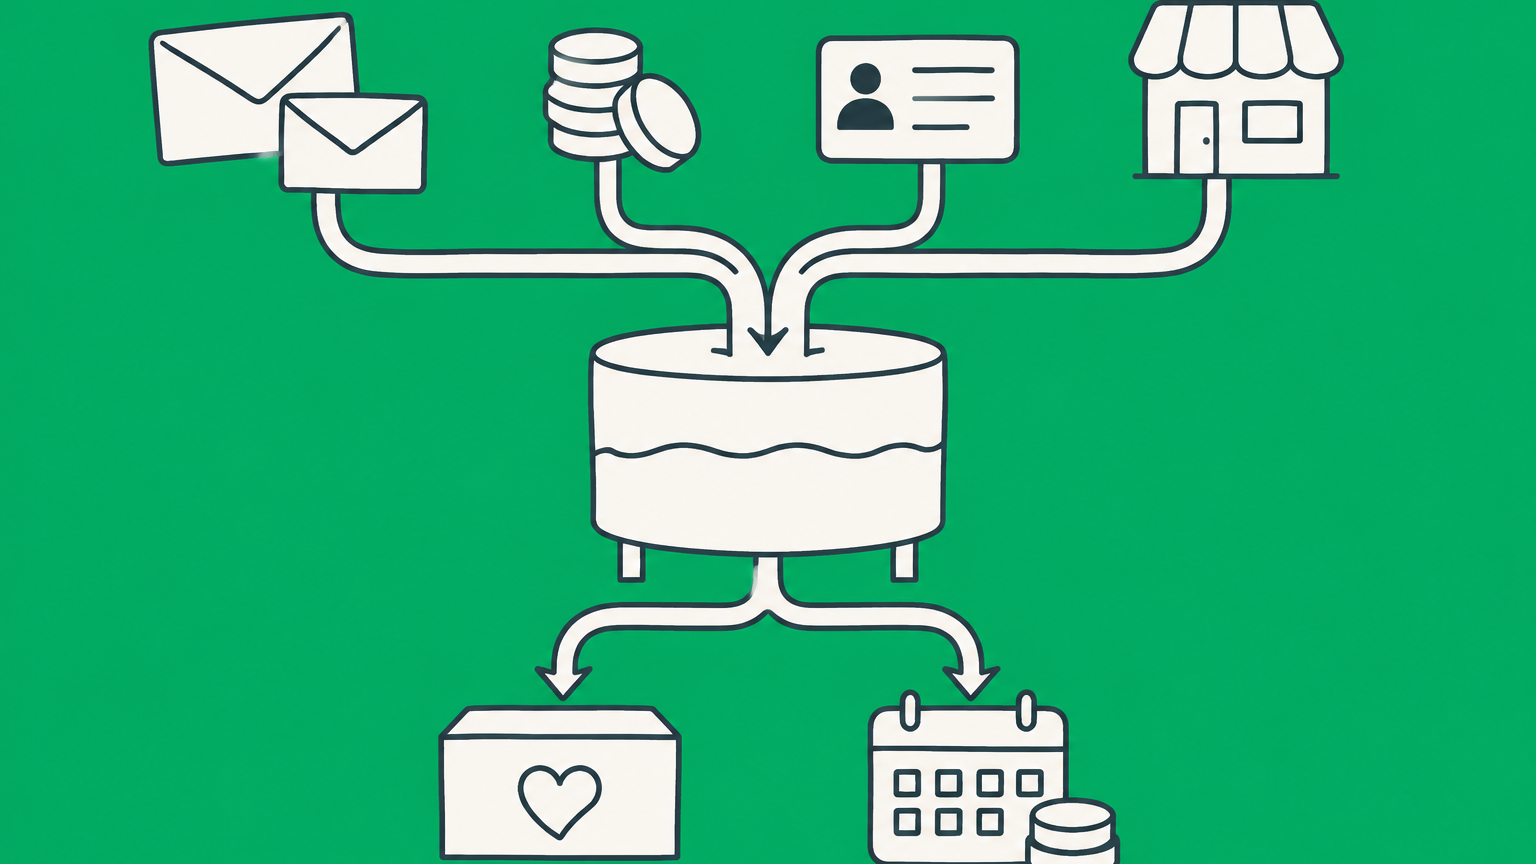
How do nonprofits make money if they cannot distribute profits to owners? They combine contributions, grants, fees, sales, investments, and other funding, then use that revenue to pay expenses, operate programs, build reserves, and advance their missions.
Key Takeaways
- Nonprofits may earn revenue and finish a year with more revenue than expenses.
- A nonprofit cannot distribute its surplus to founders, directors, or other private owners.
- Common nonprofit revenue streams include donations, grants, fees, sales, corporate support, investments, and government funding.
- Employees, founders, and executives may receive reasonable compensation for actual services.
- Federal tax exemption does not make every transaction or source of income tax-free.
- Form 990 can help the public evaluate a nonprofit's finances and reported compensation.
How Do Nonprofits Make Money? Common Revenue Streams
Nonprofit organizations need money for programs, wages, facilities, technology, fundraising, insurance, and other operating costs. The word "nonprofit" describes limits on the organization's purpose and distribution of earnings. It does not require the organization to operate without revenue or maintain a zero balance.
A nonprofit can use multiple funding sources. The right combination depends on its mission, governing documents, tax classification, donor relationships, and activities. Restrictions may come from donors, grant agreements, contracts, or tax rules.
| Revenue source | How it works | Possible restrictions | Compliance question |
|---|---|---|---|
| Donations | Individuals contribute money or property. | A donor may limit the gift to a program or purpose. | Was the contribution documented and used as promised? |
| Grants | Foundations, charities, or agencies fund defined work. | A grant may limit costs, timing, and reporting. | Does spending match the grant agreement? |
| Membership fees | Members pay for access, services, or participation. | Benefits may affect how a payment is characterized. | Are the fees connected to the exempt mission? |
| Corporate support | Businesses provide gifts, sponsorships, or in-kind help. | Advertising and substantial return benefits require review. | Is the payment a contribution or a commercial arrangement? |
| Earned income | The nonprofit sells goods, admissions, or services. | Unrelated activity may create taxable income. | Is the activity substantially related to the exempt purpose? |
| Investments | Reserves or endowments generate returns. | Donor terms may limit principal or investment income. | Do investment and spending decisions follow applicable duties? |
| Government funding | Agencies provide grants or pay under service contracts. | Funding may carry detailed performance and reporting terms. | Is the organization meeting the award or contract requirements? |
Earned income is not automatically improper. Museums may sell admission, schools may charge tuition, and nonprofit hospitals may receive payment for patient services. A nonprofit considering merchandise should review the rules for when a nonprofit can sell products.
Do Nonprofits Have Revenue, Profit, and Net Assets?
Yes, nonprofits have revenue. Gross revenue generally reflects the amounts generated or received before expenses are deducted. Expenses include program costs and supporting costs such as administration and fundraising. When annual revenue exceeds annual expenses, the organization has a surplus, often reflected in financial reporting as an increase or change in net assets.
Net assets are not simply another name for one year's profit. They generally represent the organization's assets minus its liabilities at a point in time. A nonprofit's annual operating results increase or decrease that accumulated amount. Nonprofit financial statements commonly distinguish net assets with donor restrictions from net assets without donor restrictions.
For example, assume a charity receives contributions, program fees, and grants during the year. It uses most of that revenue for services, employee compensation, rent, and fundraising, but has money remaining at year-end. The charity may retain the surplus for future programs, working capital, equipment, emergencies, or other permitted purposes. It does not have to spend every dollar before the year closes.
The central restriction is the nondistribution constraint. Unlike shareholders in a for-profit corporation, nonprofit founders and directors do not own an equity interest that entitles them to dividends or the remaining surplus. Organizational funds must support the exempt or nonprofit purpose, subject to valid expenses, contractual obligations, donor restrictions, and reasonable compensation.
This distinction helps explain what makes a nonprofit different from a for-profit business. Both may charge customers, hire staff, sign contracts, and maintain reserves. The difference lies primarily in organizational purpose, ownership rights, governance, and what can happen to net earnings.
How Nonprofits Pay Employees, Founders, and CEOs
Nonprofits pay employees from organizational revenue just as other employers do. Donations, program fees, grants, contracts, and unrestricted funds may support payroll when their terms permit it. Wages, payroll costs, and employee benefits are operating expenses, not distributions of profit.
A founder may work as an executive director, CEO, fundraiser, or program manager and receive compensation for those services. Founding the nonprofit does not create an ownership interest, however. The founder cannot take the annual surplus simply because the founder created or manages the organization.
Compensation must be reasonable rather than excessive. A sound approval process uses directors without a financial conflict, appropriate compensation comparisons, and timely documentation of the decision. The board should evaluate the person's duties, experience, working hours, organization size, location, and other relevant facts. It should also address bonuses, benefits, housing, expense reimbursements, and related-party arrangements rather than looking only at base salary.
Grant or donor restrictions can also affect payroll. A grant may authorize compensation for employees working on the funded program but prohibit unrelated administrative costs. The nonprofit should track restricted funds and allocate employee time consistently with the applicable agreement.
Paid staff members and contractors may need tax documentation even when the organization is exempt from federal income tax. The rules governing the entity's exemption do not eliminate its employer and reporting obligations. Organizations handling vendor requests can review when and how a nonprofit uses Form W-9.
Board oversight protects both the organization and the person receiving compensation. Written policies, conflict disclosures, minutes, employment agreements, and reliable payroll records help establish that payments purchase real services rather than diverting charitable assets for private benefit.
Do Nonprofits Pay Taxes? Related Income and UBIT
Nonprofits may pay taxes, even when they hold federal tax-exempt status. Exemption depends on the organization's classification and applies under specific rules. It does not mean every payment, purchase, employee, or business activity escapes taxation.
A 501(c)(3) organization generally can earn income through activities that further its exempt purpose. An educational charity might charge for mission-related classes, for example. The fact that the activity produces a surplus does not by itself make the income taxable or jeopardize exemption.
Different rules may apply when an exempt organization regularly carries on a trade or business that is not substantially related to its exempt purpose. The need to generate money for programs does not make a commercial activity mission-related. Income fitting the federal definition may create unrelated business income tax, commonly called UBIT. The IRS explains the basic elements of unrelated business income, but exclusions, exceptions, deductions, and activity-specific rules can change the result.
A nonprofit may also have employment tax obligations. State and local rules can impose sales, use, property, franchise, or other taxes, and state exemptions may require separate applications. Federal recognition should not be treated as automatic exemption from every state or local tax.
If your nonprofit plans earned-income activities, approves founder or executive compensation, or cannot determine whether revenue could create UBIT or threaten exemption, you can post your legal need on UpCounsel's marketplace. An attorney can review the activity, governing documents, compensation process, contracts, and federal tax-exemption implications. Responses typically arrive within a day, helping the board identify issues before signing agreements or committing organizational funds.
Can a 501(c)(3) Make a Profit and Keep Its Exemption?
A 501(c)(3) can generate an annual surplus while retaining its exemption. The organization must remain organized and operated for qualifying exempt purposes, and its net earnings cannot inure to insiders. It also must avoid operating primarily for private interests rather than public or charitable purposes.
The board should consider how each revenue activity supports the mission. Relevant questions include what the nonprofit sells, who receives the service, how prices are set, how frequently the activity occurs, and how the work relates to the exempt purpose. Simply transferring commercial profits into charitable programs does not necessarily make the underlying business activity related.
Organizations should also monitor broader compliance obligations. A 501(c)(3) cannot participate or intervene in a political campaign for or against a candidate for public office. Restrictions also apply to lobbying, although charitable organizations may conduct some lobbying within applicable limits. Required annual IRS filings, accurate records, donor restrictions, and appropriate governance remain important even when the nonprofit has little or no taxable income.
Private benefit and insider transactions deserve particular attention. An arrangement involving a founder, director, officer, substantial contributor, family member, or related business should have legitimate terms and a documented organizational purpose. The IRS provides guidance on inurement and private benefit.
State formation and federal exemption are separate steps. Incorporating under state law does not automatically produce 501(c)(3) recognition. Founders can review whether a nonprofit should be incorporated and the separate 501(c)(3) compliance rules that may apply after formation.
How Form 990 Shows Nonprofit Revenue and Compensation
Form 990 is an IRS information return used by many tax-exempt organizations. Depending on its circumstances, an organization may file Form 990, another return in the Form 990 series, or an electronic notice. Some organizations fall within filing exceptions, so you should confirm the form that applies instead of assuming every nonprofit files the same return.
A filed Form 990 can provide a broad picture of revenue, expenses, assets, liabilities, programs, governance, and compensation. A reader can examine contribution revenue, program-service revenue, investment income, fundraising expenses, executive compensation, contractor payments, and year-to-year changes. Schedules may supply additional information about grants, related organizations, transactions with interested persons, fundraising, and unrelated business activity.
These figures require context. High compensation does not alone prove excess, and a large surplus does not show that an organization ignored its mission. A capital campaign, restricted grant, major building project, emergency reserve, or change in accounting period may affect the numbers. Compare multiple years and read the narrative sections and schedules before drawing conclusions.
You can search filings through the IRS Tax Exempt Organization Search and review official information about Form 990. Organizations should keep financial records that support their returns and public statements. Depending on governing documents, funders, and applicable law, an independent review or nonprofit audit may also be appropriate or required.
Building Sustainable Nonprofit Revenue Streams
A durable funding model usually avoids unnecessary dependence on one donor, grant, contract, or commercial activity. Diversification does not mean pursuing every available source. Each stream should fit the mission, staff capacity, risk tolerance, and systems for tracking restrictions and reporting results.
Start by separating restricted and unrestricted resources. Restricted money must be used consistently with the donor's enforceable terms. Unrestricted revenue gives the board more flexibility, but the organization must still use it for proper organizational purposes. A budget should show expected revenue, realistic collection timing, program costs, administrative costs, fundraising expenses, debt obligations, and reserve needs.
Before launching a new stream, estimate both direct and indirect costs. A fundraising event can produce substantial gross revenue but a modest net return after venue, promotion, staffing, processing fees, and follow-up. A product line can require inventory, insurance, sales-tax analysis, contracts, and customer support. Government contracts may create cash-flow pressure if reimbursement arrives after the nonprofit pays its costs.
The board should receive regular financial reports comparing actual results with the approved budget. It should investigate major variances, review cash availability, monitor restricted balances, and document decisions about reserves. Written gift-acceptance, compensation, conflict-of-interest, investment, and expense-reimbursement policies can improve consistency.
Finally, measure revenue in relation to mission results. A source that brings in money but consumes excessive staff time, creates legal exposure, or pulls the organization away from its purpose may not be sustainable. Strong nonprofit revenue planning supports programs, fair compensation, sound operations, and long-term public benefit rather than maximizing profit for private owners.
Frequently Asked Questions
How Do Nonprofits Make Money?
Nonprofits make money through contributions, service charges, grants, contracts, memberships, sponsorships, sales, and investment returns. The mix varies by organization and can change over time. When evaluating financial stability, look beyond total revenue and consider renewal risk, donor concentration, payment timing, fundraising cost, and the portion of funding limited to particular programs.
Do Nonprofits Have Revenue?
Yes, nonprofits have revenue, including cash and potentially recognized noncash contributions. Revenue recognition may not match the date cash enters the bank account, especially for pledges, conditional grants, and multi-period awards. That difference is one reason a financial statement can show positive revenue while the organization still experiences a short-term cash shortage.
Do Nonprofits Pay Taxes?
Yes, nonprofits can pay federal, state, and local taxes depending on their activities and exemptions. Potential obligations extend beyond income tax and may include payroll, sales, use, property, or other taxes. Because state exemptions are not uniform, an organization operating or fundraising in multiple states should check each jurisdiction's current registration and tax instructions.
Can a 501(c)(3) Make a Profit?
Yes, a 501(c)(3) can end a year with revenue above expenses and may place the surplus in a reserve. A board-designated reserve remains part of the organization's assets and can generally be redirected by the board, unlike funds carrying enforceable donor restrictions. Clear reserve policies explain the reserve's purpose, target, approval process, and permitted uses.
What Is the 33% Rule for Nonprofits?
There is no universal 33% rule governing nonprofit overhead, salaries, or permissible profit. The phrase often refers to one of the IRS public-support calculations, which use detailed definitions, measurement periods, exceptions, and alternative tests. The correct analysis depends on the organization's classification and sources of support, so a simple one-third formula should not be applied without reviewing current IRS instructions.
Does the CEO of a Nonprofit Organization Get Paid?
Yes, a nonprofit CEO can receive salary, benefits, and other reasonable compensation approved for genuine services. If the CEO also sits on the board, the organization should manage that conflict carefully and exclude the CEO from voting on personal compensation. The board should evaluate total compensation, not just salary, and record the information considered and decision reached.


