A bespoke tranche opportunity is a customized structured-finance transaction that gives an investor exposure to a selected slice of credit risk. It is commonly described as a bespoke or single-tranche synthetic collateralized debt obligation, not a venture capital investment released when a startup reaches milestones.
Key Takeaways
- A bespoke tranche opportunity, or BTO, provides customized exposure to a defined range of losses within a reference credit portfolio.
- BTOs differ from conventional CDOs because the portfolio, risk attachment points, payment terms, and other provisions may be negotiated for particular investors.
- These are generally private institutional products, so you should not expect a public market price or an ordinary retail purchasing process.
- Current availability cannot be established from an old article or product label. Review recent offering materials and transaction documents.
- Shorting a BTO is not usually comparable to shorting publicly traded stock.
- Material risks include defaults, correlation, valuation uncertainty, illiquidity, counterparty exposure, conflicts, and document-specific legal terms.
Bespoke Tranche Opportunity Definition
A bespoke tranche opportunity is a customized credit product built around a portfolio of referenced obligations. Those obligations may include corporate debt or credit default swap references. Instead of buying every risk layer in the portfolio, an investor takes exposure to a negotiated tranche representing a defined range of portfolio losses.
The word "bespoke" means the parties can customize important economic terms. These may include the reference entities, maturity, tranche boundaries, payment formula, credit events, settlement process, and conditions for replacing or removing references. A customized reference portfolio is sometimes described informally as a bespoke index, although the governing documents determine what the investor actually owns or references.
The product is usually associated with synthetic CDO structures because returns can depend on contractual credit exposure rather than ownership of the referenced bonds or loans. The investor's rights come from the transaction documents, not merely from the performance of a pool described in marketing materials.
This meaning must be separated from milestone-based startup financing. In a startup transaction, an investor may promise capital in several installments, with each installment released after the company satisfies agreed conditions. That arrangement may also use the word "tranche," but it is not a bespoke CDO. Founders considering staged equity funding should instead examine the rights of minority investors and the financing agreement's milestone provisions. Searches for a "bespoke tranch opportunity," "bespoke traunch opportunity," or "bespoke tranche oppurtunity" generally refer to the same structured product, despite the misspellings.
How a Bespoke Tranche Works
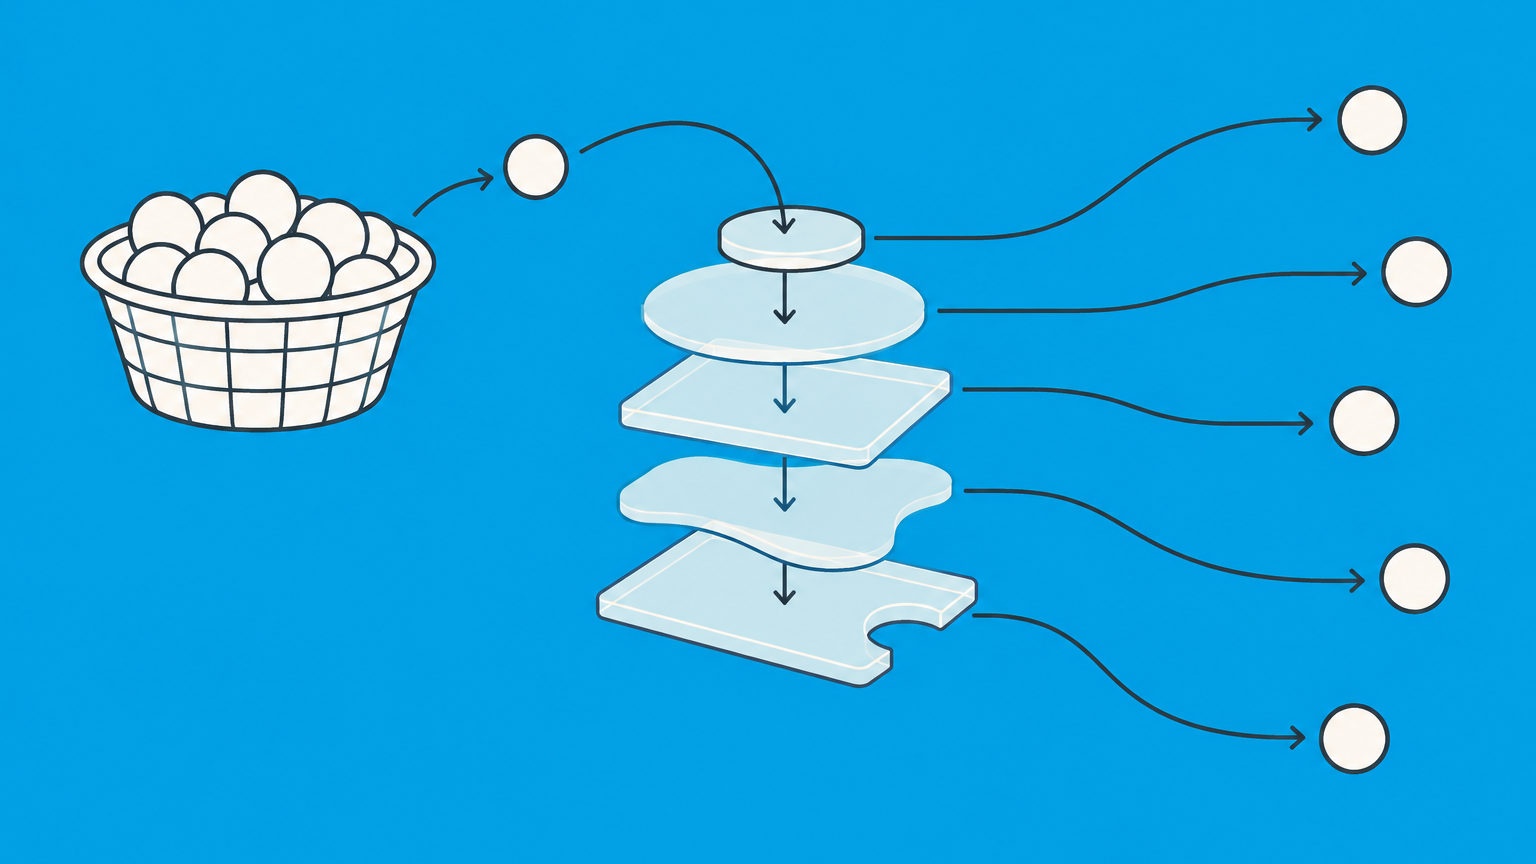
The transaction begins with a reference portfolio and a set of contractual rules. The parties then select the slice of portfolio risk that the investor will bear. Lower-risk layers generally absorb losses later, while more junior layers begin absorbing losses sooner. The documents establish where the tranche starts taking losses and when its value has been exhausted.
Consider a simple payment-waterfall example without fixed numbers. A portfolio contains several referenced companies. The first layer absorbs initial credit losses. A middle layer suffers losses only after the first layer has been depleted. A senior layer remains protected until losses pass both lower layers. If most referenced debt performs, the investor may continue receiving the payment specified for its tranche. If several correlated defaults occur, losses can reach that tranche much faster than a review of each company in isolation might suggest.
A BTO can be arranged as a funded investment or through derivative-based exposure, depending on its documents. Payments may depend on premiums, interest, principal, credit events, recoveries, collateral, and termination calculations. The investor also faces the creditworthiness of relevant counterparties and service providers.
Models help estimate default probability, recovery, and the likelihood that several references will deteriorate together. However, a model does not override the contract. Definitions of a credit event, calculation-agent discretion, valuation procedures, and settlement provisions can materially change the result. Businesses evaluating broader lending and funding arrangements can compare the roles of commercial finance companies, which provide different products and services.
Bespoke Tranche Opportunity vs. CDO and Other Tranches
The terms BTO, CDO, debt tranche, and investment tranche all involve dividing exposure, but they do not describe interchangeable products. The following comparison provides a starting point. The applicable term sheet, confirmation, offering document, and related contracts control the actual transaction.
| Feature | Bespoke Tranche Opportunity | Conventional CDO | Generic Debt Tranche | Startup Investment Tranche |
|---|---|---|---|---|
| Customization | Negotiated portfolio and risk slice | Structure generally established for a broader issuance | Terms set within a loan or securities offering | Funding schedule and milestones negotiated by the company and investor |
| Underlying exposure | Often synthetic exposure to selected credit references | Debt assets, synthetic references, or a combination, depending on the structure | A loan, bond issue, or other debt facility | Equity, convertible rights, or debt issued by a business |
| Payment priority | Defined by customized loss boundaries and contractual waterfall | Different classes receive payments and losses according to an established waterfall | Depends on seniority, collateral, and subordination | Capital is released when contractual conditions are met |
| Typical access | Private institutional transaction | Institutional market, subject to the particular offering | Varies from private lending to publicly offered securities | Private company and venture investors |
| Liquidity | Potentially limited and document-dependent | Varies by product, market, and class | Ranges from actively traded to nontransferable | Usually limited because the company is privately held |
| Primary risks | Correlation, model, valuation, counterparty, liquidity, and documentation risk | Asset quality, waterfall, leverage, market, and liquidity risk | Borrower default, interest-rate, collateral, and priority risk | Company performance, dilution, milestone disputes, and loss of invested capital |
A BTO can be described as a customized form of CDO exposure, but that shorthand does not reveal its complete economics. Two transactions using the same label may have different portfolios, tranche boundaries, collateral arrangements, or termination rights. The distinction also matters legally because finance contracts allocate payment, default, enforcement, and transfer rights through their specific language.
Do Bespoke Tranche Opportunities Still Exist in 2026?
Customized credit tranches may still be privately arranged in 2026, but product names and market practices change. A webpage labeled "bespoke tranche opportunity 2020" or "bespoke tranche opportunity 2025" does not prove that a particular product is currently offered, transferable, or available to a specific investor. Confirmation requires recent primary transaction materials and information from an authorized market participant.
CDOs also continue to exist as a category of structured finance, although structures, underlying exposures, distribution methods, and regulatory requirements can differ from pre-2008 products. Some current transactions may use terms such as bespoke tranche, synthetic tranche, or correlation product instead of BTO. Similar terminology does not make their risks identical.
When assessing a current opportunity, request documents that identify the issuer or counterparties, reference portfolio, tranche boundaries, maturity, collateral, payment waterfall, valuation process, and transfer rules. Determine which entity is offering the exposure and what role each dealer, arranger, calculation agent, trustee, or collateral provider performs.
Also verify investor eligibility and applicable securities or derivatives requirements. Private availability to a financial institution does not establish access for an individual investor. A discussion forum, advertisement, or indicative presentation is not a substitute for executed documents or a current offering package.
Bespoke Tranche Opportunity Price, Sellers, and Access
There is no single public bespoke tranche opportunity price. Pricing depends on the selected reference portfolio, expected defaults, recovery assumptions, correlation, maturity, tranche boundaries, market conditions, collateral, counterparty credit, and negotiated contractual terms. Because the product is customized, a price or yield quoted for one transaction may have little relevance to another.
Dealers, investment banks, or other structured-credit market participants may arrange or intermediate bespoke exposure, subject to applicable rules and the parties' eligibility. The governing documents determine who legally issues, sells, guarantees, or acts as counterparty to the product. They also determine whether the investor can transfer its position, obtain dealer consent, or sell only to an eligible transferee.
Limited trading can make valuation difficult. An investor may receive an indicative dealer mark rather than an executable market price. A model valuation may also rely on assumptions that become unreliable during stressed markets. Before treating any quoted value as realizable, ask how the position would be valued for collateral, financial reporting, termination, and an actual transfer.
Institutional structures may use special-purpose entities or private investment vehicles. Understanding the entity holding the position can be as important as understanding the tranche itself. Review how a private investment company is formed and operated when the proposed investment will sit within a private vehicle.
Before signing or negotiating documents for a customized structured product, you can post your legal need on UpCounsel's marketplace. An attorney can review the reference portfolio definitions, payment waterfall, representations, default and termination provisions, disclosure duties, counterparty terms, and transfer restrictions. Counsel can also identify conflicts between the term sheet and definitive agreements. Responses typically arrive within a day, helping you address document issues before committing capital or accepting contractual exposure.
How to Short a Bespoke Tranche Opportunity
Shorting a BTO usually does not mean borrowing a publicly traded security and selling it through a retail brokerage account. The product may be private, nontransferable, or created for one transaction. A person seeking bearish exposure generally must determine whether a dealer or counterparty will arrange an offsetting or economically inverse credit position.
Possible structures could include purchasing credit protection on selected references, taking exposure to a tranche that benefits from defined credit losses, or negotiating a separate derivative. None automatically creates a perfect short. The proposed position may use different reference entities, maturities, credit-event definitions, attachment points, or settlement rules. Those differences create basis risk, meaning the hedge and the original exposure may not move together.
Access presents another obstacle. A counterparty may require financial sophistication, trading documentation, collateral, margin, and minimum transaction size. The position may also produce losses before the anticipated defaults occur. Premium obligations, changing collateral requirements, early termination, counterparty failure, and mark-to-market movements can make a directionally correct view unprofitable.
Review the master agreement, confirmation, credit support terms, close-out methodology, tax treatment, and transfer restrictions before discussing execution. A customized transaction is also a form of bespoke contract, so small wording differences can materially affect the result. Do not assume that a strategy described for a standardized credit index can be applied to a private bespoke tranche.
BTO Risks, the 2008 Comparison, and Crash Concerns
Bespoke tranches raise legitimate concerns associated with structured credit, but claims that every BTO will cause a crash or represents a new bubble go beyond what the product label proves. The better approach is to test each transaction for transparency, valuation reliability, liquidity, counterparty exposure, conflicts, and sensitivity to clustered defaults.
- Credit and correlation risk: Several references can deteriorate together, causing losses to move rapidly through the waterfall.
- Model risk: Default, recovery, and correlation assumptions may not reflect stressed market behavior.
- Liquidity risk: A customized position may lack willing buyers when the investor needs to exit.
- Valuation risk: Dealer marks and models may produce materially different values, particularly during volatile periods.
- Counterparty risk: Expected payments may depend on a dealer, guarantor, collateral provider, or other contractual party remaining able to perform.
- Legal and documentation risk: Ambiguous credit events, substitution rights, calculation discretion, or termination formulas can change economic outcomes.
- Conflict risk: An arranger or calculation agent may perform several roles, making conflict disclosures and contractual standards significant.
The 2008 comparison requires precision. CDOs and synthetic credit structures were part of the broader structured-finance market associated with the financial crisis, particularly where mortgage-related exposure, leverage, weak underwriting, and underestimated correlation interacted. That history does not establish that every present-day corporate-credit BTO has the same assets or mechanics. It does show why investors should test assumptions rather than rely only on ratings, labels, or recent performance.
Online discussions may focus on a bespoke tranche opportunity crash or bubble. Those predictions should be evaluated against actual portfolio composition, outstanding exposure, leverage, interconnected counterparties, collateral arrangements, and loss scenarios. Without transaction-level information, a dramatic market prediction remains speculation rather than a product analysis.
Frequently Asked Questions
How Do You Short a Bespoke Tranche Opportunity?
You generally need a dealer or qualified counterparty to structure an inverse or offsetting credit position. Start by identifying the exact reference portfolio and contractual loss range you want to oppose. Then compare maturities, credit-event definitions, settlement methods, and collateral obligations. A superficially similar credit trade may create substantial basis risk instead of an effective short.
Do CDOs Still Exist Today?
Yes, CDOs still exist, although their assets, structures, names, and market use may differ from products sold before the financial crisis. The term alone does not indicate whether a transaction holds debt, references credit synthetically, or combines both approaches. Current offering documents are necessary to determine the structure and the investor's actual exposure.
Are CDOs Still a Thing for Individual Investors?
CDOs remain part of institutional structured finance, but direct access for individual investors is generally limited and depends on the offering. Retail investors should not assume that an online description represents an available security. Eligibility requirements, denomination, distribution restrictions, suitability standards, and transfer limitations may prevent or restrict participation in a particular transaction.
Do Bespoke Tranche Opportunities Still Exist?
Yes, customized tranche transactions may still be arranged, but the BTO label is not used consistently across the market. Evidence of a current opportunity should include a recent term sheet, identified counterparties, defined reference obligations, pricing terms, and applicable offering documents. An older article or discussion thread cannot confirm present availability.
What Is the 40-40-20 Rule in Investing?
The 40-40-20 rule is not a single, universally accepted investment standard. Different commentators use the percentages for different allocation, budgeting, or portfolio approaches. Before applying it, identify what each percentage represents and consider your time horizon, liquidity needs, diversification, taxes, and capacity for loss. It is unrelated to the payment waterfall of a bespoke tranche.
Is Buy and Hold Still a Good Strategy?
Buy and hold can remain appropriate for investors using diversified assets and a long time horizon, but it does not eliminate investment risk. Suitability depends on the asset, price, concentration, costs, liquidity needs, and personal objectives. Holding an opaque or highly concentrated structured product indefinitely is not equivalent to holding a diversified public-market portfolio.


