Cooperative vs corporation is a comparison between member-centered ownership and a conventional corporate model. The right choice affects voting power, financing, profit distribution, management, taxes, and ownership transfers.
Key Takeaways
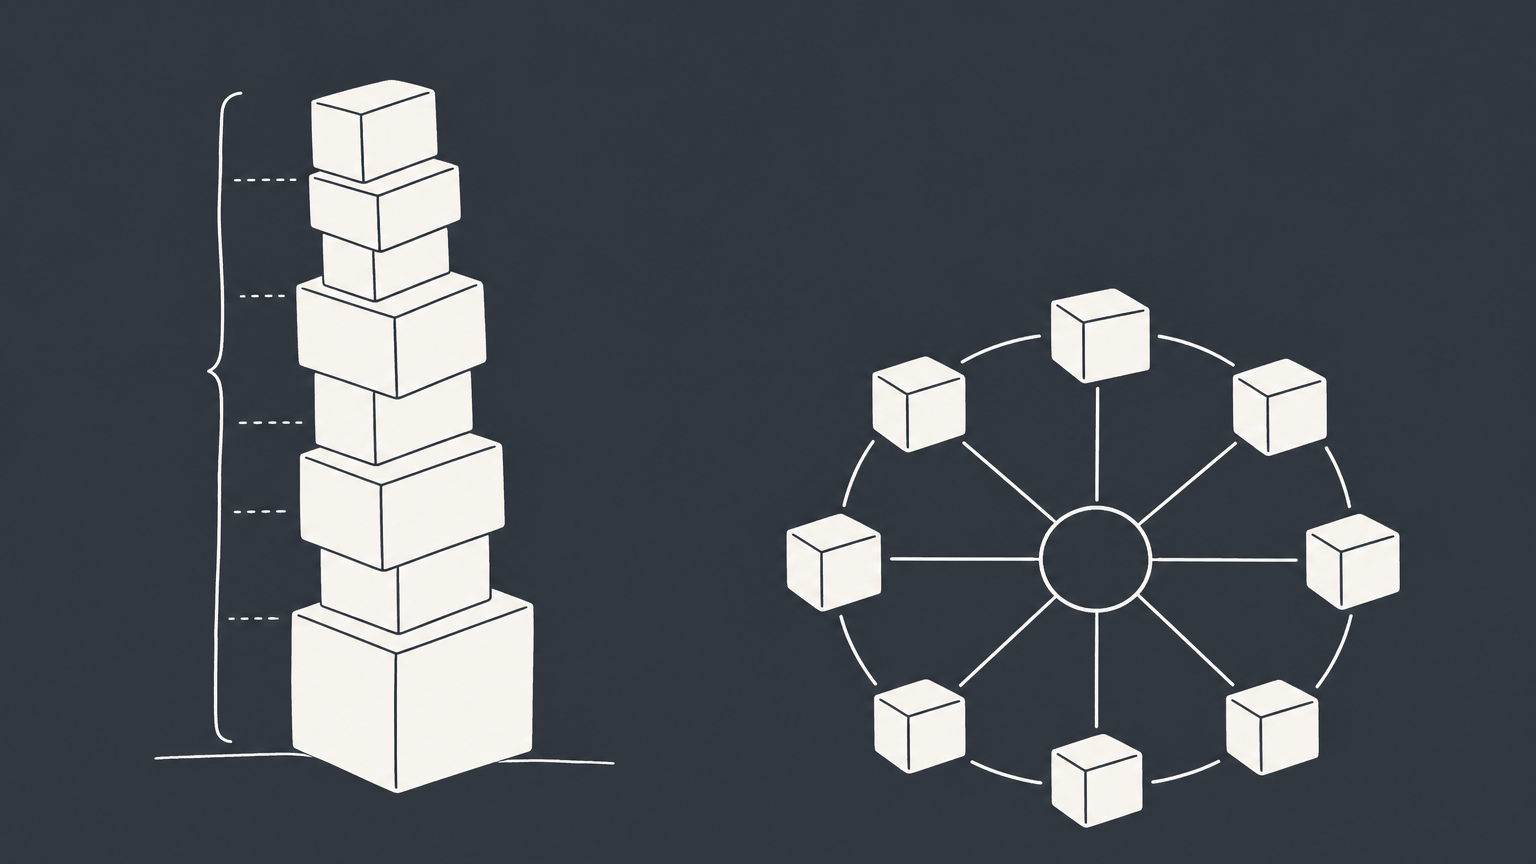
- A business corporation is generally controlled by shareholders, while a cooperative is controlled by members who use, work for, or produce through the business.
- Corporate voting usually tracks share ownership. Cooperative voting commonly follows one member, one vote, subject to governing law and documents.
- Corporate dividends generally reflect equity ownership. Cooperative distributions may reflect member participation or patronage rather than equal division.
- Corporations usually offer a more familiar structure for outside equity investors. Cooperatives often rely more heavily on members, retained earnings, and debt.
- A cooperative may use a cooperative corporation, another corporate form, or sometimes an LLC, depending on state law.
- Tax results depend on the legal entity, tax election, jurisdiction, and method of distributing earnings.
Cooperative vs Corporation at a Glance
The main difference between a corporation and cooperative is not simply that one earns profits and the other serves a community. Both can operate businesses, hire employees, enter contracts, own assets, and generate revenue. The central distinction is how ownership, control, and economic benefits are organized.
| Issue | Corporation | Cooperative |
|---|---|---|
| Ownership | Usually owned by shareholders | Owned by participating members |
| Voting | Usually based on shares or classes of stock | Commonly one member, one vote |
| Management | Shareholders elect directors, and officers manage operations | Members elect directors, and a board, officers, or managers run operations |
| Profits or surplus | May be retained or paid as dividends based on equity rights | May be retained or returned based on patronage or participation |
| Capital | Can issue stock and seek outside equity | Often uses member contributions, retained earnings, loans, and limited outside capital |
| Transfers | Shares may be transferable, subject to law and restrictions | Membership interests are often restricted or subject to approval |
| Liability | Owners generally receive limited liability | Liability protection depends on the entity form and applicable law |
| Taxation | Depends on corporate type and tax elections | Depends on entity form, distributions, activities, and tax rules |
| Formation | Files formation documents and adopts governance documents | Follows the available state statute and adopts member-centered governance terms |
These are general patterns, not universal rules. State law, articles, bylaws, shareholder agreements, membership terms, securities rules, and tax elections can change the result.
What Is a Corporation?
A corporation is a legal entity separate from its owners. A business corporation can hold property, make contracts, incur debts, sue or be sued, and continue despite changes in ownership. Shareholders generally receive limited liability, although that protection can be affected by personal guarantees, misconduct, or failure to respect the entity's separate existence.
Shareholders elect a board of directors. The board sets major policy, approves significant transactions, and appoints officers. Officers and employees then manage daily operations. Voting power commonly depends on the number and class of shares, but articles, bylaws, and shareholder agreements may create different rights or restrictions.
Not every corporation exists solely to maximize shareholder profit. Some corporations pursue broader purposes, and nonprofit corporations follow a different ownership model. Private corporations can also limit transfers, require approval before a sale, or give existing owners a right to purchase shares. Corporate stock is therefore not always freely transferable.
Corporations may retain earnings or distribute dividends when legally permitted and properly authorized. The rights attached to a dividend can depend on the class of stock. Founders considering this structure should understand the required corporate organizational documents, including formation documents, bylaws, board actions, and ownership records.
What Is a Cooperative and Can It Be a Corporation?
A cooperative is a member-owned business organized to meet shared economic or service needs. Members may be customers, workers, producers, residents, or other participants. Instead of giving control primarily to outside investors, the cooperative model connects ownership and governance to membership.
A cooperative can be a corporation, but the answer depends on the legal form selected under state law. Some groups incorporate under a specific cooperative statute. Others may use a standard corporation with cooperative provisions where permitted. In some jurisdictions, an LLC may also operate using cooperative principles. The group's filing documents and applicable statute determine the legal entity, while its ownership and governance arrangements determine how cooperatively it operates.
The common one-member, one-vote rule prevents a member with more capital from automatically gaining more control. It is a general cooperative principle, however, and the precise voting system must comply with governing law and organizational documents. Cooperative earnings are also not necessarily divided equally. A cooperative may retain them, place them in reserves, or make distributions based on how much business each member conducts with the cooperative.
Membership does not have to be local. A cooperative may serve a defined community, but it can also cover a large region or a specialized group. For a broader explanation of governing rules and member rights, review how cooperative law works.
Corporation and Cooperative Differences in Control and Economics
Corporate governance separates ownership from day-to-day management. Shareholders vote on matters reserved to them and elect directors, but they do not ordinarily manage routine operations. A shareholder with a large voting position may have substantial influence over the board and major transactions.
Cooperatives also commonly use a board. Members elect directors, and the board can hire officers, a chief executive officer, or other managers. Having a CEO does not make the organization less cooperative. The key question is who ultimately holds the voting rights and how authority is divided among members, directors, officers, and management.
The economic distinction is equally significant. A corporation can pay dividends according to stock rights, so a shareholder with more dividend-bearing shares may receive more. A cooperative may make patronage distributions tied to a member's transactions, labor, production, or use of the enterprise. The formula should appear in the bylaws, membership agreement, or other governing documents and must follow applicable law.
Each model involves a governance tradeoff. Weighted shareholder voting can support decisive control and accommodate investors with different financial rights. Democratic member voting protects member control but may require more consultation and education. Large cooperative memberships can also make meetings, elections, and consensus building more demanding. Neither system guarantees good management. Clear procedures, accurate records, conflict rules, and defined board authority remain necessary under both models.
Taxes, Financing, Liability, and Ownership Transfers
A corporation vs cooperative tax comparison has no single answer. A C corporation generally pays tax at the entity level, and shareholders may also owe tax when they receive taxable dividends. An eligible corporation may elect another federal tax treatment, such as S corporation status. Cooperative taxation can depend on its legal form, activities, member and nonmember business, and treatment of patronage distributions. State taxes can differ from federal rules.
Do not choose a cooperative solely because someone describes it as tax-advantaged. Confirm the expected treatment with current federal and state guidance based on the proposed entity, ownership, operations, and distribution plan. The same caution applies to corporations because a tax election does not replace the underlying state-law entity.
Financing often creates the clearest practical divide. A corporation can create stock classes and offer equity to investors, subject to corporate and securities laws. Investors may expect voting rights, preferential economic terms, or a future sale. A cooperative commonly protects member control, which can make conventional outside equity harder to structure. It may instead rely on member capital, retained earnings, loans, or financing designed around cooperative ownership.
Both structures can provide limited liability when properly formed and maintained, but the applicable entity statute controls. Transferability also varies. Corporate transfer restrictions can appear in agreements or governing documents. Cooperative memberships may be nontransferable, redeemable, or transferable only with approval. Those restrictions protect membership standards but can make an owner's exit less flexible. Formation budgets should account for filing charges and other corporate fees and state costs.
How to Choose Between a Cooperative and Corporation
Start with control. A corporation may fit if founders want voting power to follow investment, need multiple equity classes, plan to seek conventional outside capital, or expect owners to sell their interests. It also provides investors and advisers with a familiar board and shareholder framework.
A cooperative may fit if the people using or supplying the business should control it. Examples include employees seeking worker ownership, customers organizing shared purchasing, producers marketing goods together, or residents managing housing. Cooperative ownership can align decision-making with participation rather than invested capital.
Classification systems vary, so there is no universal list of exactly three cooperative types. Common categories based on the member group or purpose include:
- Consumer cooperatives: Customers own an enterprise that supplies goods or services.
- Worker cooperatives: Workers own and participate in governing their workplace.
- Producer cooperatives: Producers, including agricultural producers, combine processing, purchasing, or marketing activities.
- Housing cooperatives: Members organize around rights to occupy or use housing.
- Service or utility cooperatives: Members organize to obtain a shared service.
Consider the disadvantages as well. Cooperative decision-making may take more time, member participation can vary, and restrictions designed to preserve member control may limit outside investment or exit options. Corporations can raise capital more flexibly, but investors with larger positions may gain more influence. Corporate formalities and reporting obligations can also require continuing attention.
Your decision should reflect the expected investors, members, voting system, distribution method, transfer plan, and long-term exit strategy. Do not rely on the entity's name alone.
Formation Documents and State-Law Requirements
To form a corporation, organizers generally file formation documents with the appropriate state office and adopt bylaws. The corporation then completes organizational actions, appoints directors and officers, authorizes ownership interests, and creates the records required for its operations. The specific filings, fees, and recordkeeping rules vary by jurisdiction.
Cooperative organizers must first identify which structures their state permits. A dedicated cooperative statute may set requirements for the entity's name, purpose, membership, board, voting, distributions, and dissolution. If the group plans to use a conventional corporation or LLC, its organizers must confirm that the selected statute and governing documents can support the intended cooperative features.
The documents should address eligibility for membership, admission and termination, member contributions, voting, board authority, management, distributions, reserves, transfer restrictions, redemptions, disputes, and dissolution. If the business uses an S corporation election, its organizers should also review the relationship between ownership terms and S corporation bylaws.
When your group is ready to select an entity, allocate voting and economic rights, raise outside capital, or convert an existing business, you can post your legal need on UpCounsel's marketplace. An attorney can compare structures permitted by state law and draft or review formation documents, bylaws, membership terms, transfer restrictions, and governance provisions. Responses typically arrive within a day.
Before filing, model what happens when a member leaves, dies, stops participating, or wants to sell an interest. Also decide who can amend the governing documents and approve a merger, conversion, or sale. Addressing these events early can prevent later disputes over control and value.
Cooperate vs Corporate and Other Similar Terms
The words corporation, cooperative, cooperation, corporate, and cooperate sound similar but serve different grammatical and legal functions. Using the correct term matters in formation documents, contracts, correspondence, and ordinary business writing.
- Corporation: A type of legal entity formed under an applicable incorporation statute.
- Corporate: An adjective describing something related to a corporation, such as corporate records or corporate governance.
- Cooperative: A member-owned organization or an adjective describing collaborative conduct or a cooperative business model.
- Cooperation: The act or process of working together. It is not a business entity.
- Cooperate: A verb meaning to work or act together toward a shared result.
For example, a business can be incorporated as a corporation, adopt corporate bylaws, and cooperate with another company. Two parties can work in cooperation without forming either a corporation or a cooperative. The standard phrase is, "Thank you for your cooperation," because the writer is thanking someone for assistance, not referring to a legal entity.
The difference between corporation and cooperation is therefore a difference between an organization and an activity. The difference between cooperate and corporate is a verb-versus-adjective distinction. If you are choosing a legal structure, the relevant comparison is cooperative versus corporation, not cooperation versus corporation.
Frequently Asked Questions
What Is the Difference Between a Corporation and Cooperative?
A corporation usually connects ownership and economic rights to shares, while a cooperative connects control and benefits to membership or participation. The practical distinction appears in the voting formula, eligibility rules, distribution method, and exit rights. A filing label alone may not reveal those details, so review the statute and governing documents.
Is a Cooperative a Corporation?
A cooperative may be a corporation, but not every cooperative uses the same legal form. The answer depends on the state's available entity statutes and the organizer's filings. Check the public formation record to identify the entity type, then review its articles and bylaws to determine how member ownership and voting operate.
What Is the Difference Between Corporation and Cooperation?
A corporation is a legal organization, while cooperation means working together toward a shared objective. Cooperation does not create an entity, limited liability, ownership rights, or a governance system. People and businesses can cooperate through informal conduct or a contract without forming a new corporation or cooperative.
What Is a Cooperative Corporation?
A cooperative corporation is generally a corporation organized with cooperative ownership and governance features. The term does not identify one uniform nationwide entity. Its legal meaning depends on the incorporation statute, filed articles, bylaws, membership provisions, and any state rules governing cooperative names or operations.
What Is the Difference Between Cooperative and Cooperation?
A cooperative is an organization or business model, while cooperation is the conduct of working together. A cooperative normally has defined members, governance rules, and financial arrangements. Cooperation can occur between any people or organizations and does not, by itself, establish membership or legal rights.
Can an LLC Be a Cooperative?
An LLC may operate cooperatively where state law permits its operating agreement to establish the required member control and economic arrangements. Organizers should confirm that the LLC statute, cooperative statute, tax plan, and filing rules support the proposal. Calling an LLC a cooperative does not override conflicting legal requirements.
Can a Cooperative Have a CEO?
Yes, a cooperative can have a CEO or another executive manager. The title does not determine who owns or controls the organization. The bylaws, board resolutions, and employment terms should define the executive's authority while preserving the rights that applicable law and governing documents reserve for members and directors.


